How to Document Losses Under Mississippi Personal Injury Damage Caps
Crash expenses never arrive in one neat package. A hospital statement can land weeks before your insurer’s explanation of benefits shows up, and missed work stretches across several pay periods while the small costs vanish entirely unless you write them down on the spot.
Start by classifying each loss. Mississippi treats measurable financial losses one way and pain another, so your records need to show which is which. A dated bill tied to the crash shows what happened; a rough guess scribbled months later does not. Label everything early.
Separate Financial Losses From Personal Harm
What Counts as an Economic Loss
Economic damages are financial losses you can prove with paperwork. Medical statements and wage records are the obvious ones. Repair invoices, pharmacy receipts, mileage logs, and written future-care estimates count too.
Each charge must also connect to the crash. A dated bill or a record created at the time, from a provider or employer, carries far more weight than an unsupported figure written after the fact.
What Counts as Non-Economic Harm
Non-economic damages cover the subjective side: pain, emotional distress, loss of enjoyment of life. Treatment notes and a factual daily journal can document those harms, but they don’t belong in your expense ledger.
That split has real consequences. Mississippi’s caps reach the subjective side of a claim while verifiable losses like medical bills sit outside them, so knowing where Mississippi caps on injury compensation apply before you build your file keeps the right costs in the right column. Good documentation supports a claim; it doesn’t guarantee payment or a specific outcome.
The Mississippi provisions relevant to these issues include Miss. Code Ann. §§ 11-1-60, 11-1-65, 15-1-49, and 11-46-11. Section 11-46-11 addresses filing deadlines and claims governed by the Mississippi Tort Claims Act.
| Record Category | Economic or Non-Economic | Useful Supporting Record |
|---|---|---|
| Hospital treatment costs | Medical expense | Medical bill and explanation of benefits |
| Missed hourly work | Economic | Payroll history and employer confirmation |
| Travel for treatment | Economic | Dated mileage log and appointment record |
| Pain affecting sleep | Non-economic | Treatment note or dated personal journal |
| Reduced enjoyment of activities | Non-economic | Specific dated account of the missed activity |
A document shows that you incurred a cost. It obligates no insurer to accept the loss, and it proves no liability on its own.
Build One File Before Records Scatter
Create Digital and Paper Copies
Keep one physical folder and one backed-up digital folder. Name each file date first, then source and amount: 2026-08-14-Clinic-Statement-185.pdf. The pattern sounds fussy until you need one receipt out of eighty.
Start a Master Loss Ledger
Create a spreadsheet or notebook with a column for each of the following:
- Date incurred
- Expense or income-loss category
- Provider or source
- Amount charged
- Amount paid
- Insurance payment or adjustment
- Outstanding balance
- Supporting file name
- Notes connecting the loss to the crash
Keep the provider’s charge separate from the insurer’s payment and your remaining balance. Combine them, and you’ll count the same dollar twice.
Preserve Originals and Record Their Source
Keep the original statement or receipt whenever you can. Screenshots need the date, the sender, and the complete transaction, not just a cropped dollar amount.
Back everything up monthly to a secure location. Never upload medical or financial records to a publicly accessible shared folder.
Save Medical and Recovery Costs
Match Bills to Treatment Records
Collect itemized provider bills and pharmacy receipts. Add your insurer’s explanation of benefits and any payment confirmation. Appointment summaries tie each bill to a specific visit.
One caution: an explanation of benefits is not a bill. Don’t record it as an extra expense. Your ledger separates the provider’s charge from the insurer’s adjustment and payment, with your remaining balance in its own column.
Track Travel and Incidental Treatment Costs
Track mileage, parking fees, and tolls. Record prescribed equipment, home-health assistance, and necessary modifications to your home or vehicle as well.
Every mileage entry needs the date, route, medical purpose, and distance. Don’t apply a business mileage rate on your own. Record the actual travel; the appropriate professional determines its potential value.
Medical expenses sit outside Mississippi’s non-economic damages cap under Miss. Code Ann. § 11-1-60. Documentation and crash-related causation still determine whether you can recover an expense, so keep every record tied to the collision.
Prove Lost Income and Missed Work
Records for Employees
Gather recent pay stubs and your pre-crash wage history, plus work schedules and attendance records. Ask your employer for a signed statement covering the missed dates, hours, and pay rate. Note any established overtime pattern and leave used.
A self-written estimate alone won’t carry the weight of payroll and employer records. It needs independent support.
Records for Self-Employed Workers
Self-employed income swings, so one canceled invoice rarely tells the whole story. Tax returns and profit-and-loss statements show the pattern. Bank deposits and appointment calendars can confirm it, while contracts and written cancellation records explain the gaps.
Keep gross revenue separate from net income. Keep business expenses that would have occurred anyway separate from your personal lost-earnings calculation.
Used Leave and Lost Benefits
Crash-related absences that burn vacation or sick time may support an economic-loss claim, so preserve the payroll entries and your employer’s leave policy. Documented lost bonuses and commissions may matter too, along with reduced retirement contributions or employer-paid benefits.
Reduced Capacity After Returning
You can return to work and still lose income through shorter shifts or modified duties. Fewer clients and missed advancement opportunities may fit the same category. Preserve schedule changes and written work restrictions, and skip the speculative career projections. Future earning-loss claims generally need stronger vocational and medical support than a personal estimate.
Record Property and Recurring Out-of-Pocket Costs
Connect Each Payment to a Specific Need
Save towing and storage invoices, repair estimates, and rental receipts for replacement transportation. Keep records for damaged personal property too.
Childcare required for treatment, and paid household help made necessary by crash-related limitations, may support a claim. Ordinary household spending doesn’t, unless the crash created an added, documented cost.
Recurring charges need their own dated entries even when the amount never changes. Note the service period and retain the invoice or payment confirmation.
Reconstruct Missing Records Carefully
Replace Lost Receipts With Independent Records
A lost paper receipt doesn’t end your documentation effort. Request duplicate invoices, pharmacy histories, and patient account statements. Card records and email confirmations fill other gaps.
A card statement proves a payment occurred, but it may not show what you bought or how the purchase relates to the crash. Pair it with another record whenever possible.
Reconcile Records From Several Providers
Request a separate account history from each provider. One emergency visit can generate a hospital bill plus separate charges from the physician group and the imaging center. Compare dates and service descriptions before assuming any statement is a duplicate.
Explain Gaps Without Inventing Details
If a record stays missing, write a dated note explaining what’s missing, whom you contacted, and when you requested a replacement. Never recreate a receipt. Never guess at an amount.
How Mississippi Personal Injury Damage Caps Affect Your Records
Are Medical Expenses and Lost Wages Capped?
No. Mississippi’s general non-economic damages cap leaves objectively verifiable economic losses such as crash-related medical expenses and lost earnings uncapped. Miss. Code Ann. § 11-1-60 defines economic and noneconomic damages and limits noneconomic-damages awards; it does not establish the elements or types of damages recoverable in a collision claim.
Recoverability also turns on proof, causation, available coverage, and fault.
What Is the Mississippi Pain and Suffering Damages Cap?
Miss. Code Ann. § 11-1-60 generally limits non-economic damages in covered civil actions to $1 million. Pain and suffering is the classic example, because it concerns the physical discomfort and emotional strain of an injury, not the cost of treating it. The limit is a ceiling. It guarantees no award.
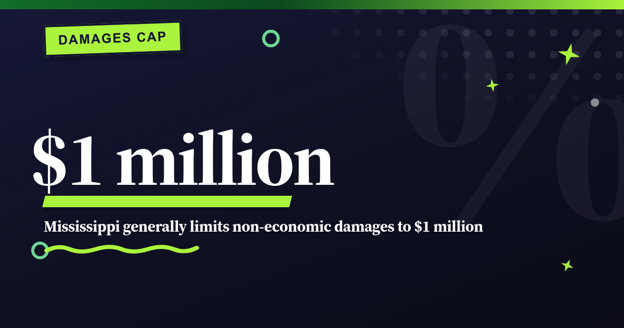
This cap applies in covered civil actions under § 11-1-60.
How Do Damage Caps Affect Mississippi Settlements?
A statutory cap can shape negotiations around the legally recoverable non-economic portion of a claim, but it does not set a settlement amount. Insurers may still dispute fault, coverage, causation, or the reasonableness of a documented loss.
A clear ledger keeps measurable expenses separate from non-economic harm while the parties evaluate and negotiate.
What Is the Mississippi Punitive Damages Cap?
Punitive damages punish qualifying misconduct, not compensate for bills or lost income. Under Miss. Code Ann. § 11-1-65, Mississippi applies separate limits based on the defendant’s net worth, so no single punitive cap covers every defendant.
Watch the Filing Deadline While Gathering Records
Mississippi’s General Personal Injury Time Limit
Miss. Code Ann. § 15-1-49 generally provides a three-year limitations period for actions without another prescribed deadline. Many Mississippi personal injury actions must be filed within three years, but the deadline shifts with the defendant, the claim type, and the applicable statute.
Collecting records or negotiating with an insurer doesn’t necessarily pause that clock. Mark the crash date on a calendar and confirm the deadline that applies to your claim.
What the “270-Day Law” Actually Means in Mississippi
Mississippi imposes no universal 270-day filing deadline on ordinary personal injury claims. Treat any reference to 270 days as the deadline for a private car-crash lawsuit only after identifying the specific law and claim type involved.
Claims involving government entities or employees follow specialized procedures under the Mississippi Tort Claims Act. Miss. Code Ann. § 11-46-11 includes a pre-suit notice requirement and timing rules that diverge from those governing an ordinary claim against a private party. Consult a qualified Mississippi attorney promptly if a government vehicle, public employee, or government entity may be involved.
Keep the File Current Until the Claim Ends
Update the ledger whenever a new bill or payment arrives, and after each appointment or work absence. A monthly review catches missing statements and duplicate entries while the records are still available.
Organized records make a financial-loss claim easier to evaluate, but proof doesn’t guarantee compensation. Seek individualized legal advice when deadlines or disputed expenses complicate the claim, especially when self-employment income or a government defendant raises additional issues.